


National CRE News In Your Inbox.
Sign up for Connect emails to stay informed with CRE stories that are 150 words or less.

Office Vacancy Eases in Q3 as New Supply Nears Record Lows
The U.S. office market continued its recovery in Q3, according to national reports from CBRE, JLL, Cushman & Wakefield, Colliers and Lee & Associates. All reported lower vacancy year over year, new construction fell to its lowest level in decades, and demand continued to favor higher-quality buildings.
Vacancy Declines Everywhere
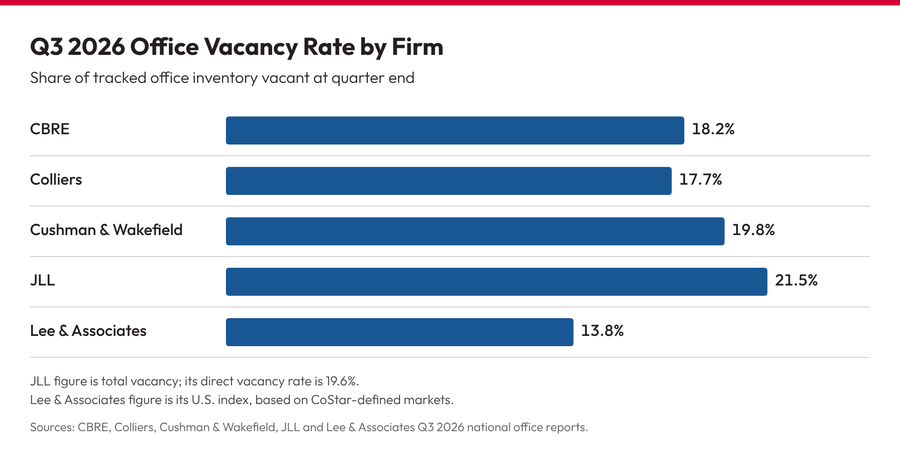
- Colliers reported a 17.7% vacancy, representing a 60 basis-point decrease from the year before, and the lowest since Q4 2023.
- CBRE also noted a 60 bps drop, with vacancy at 18.2%; a fifth consecutive quarterly decline.
- Cushman & Wakefield had vacancy at 19.8%, down 30 bps from its Q3 2025 peak.
- JLL reported a vacancy of 21.5%, while Lee & Associates ended up at 13.8%, about 20 bps below its 2025 high.
Leasing Favors the Best
CBRE said leasing rose 4% year-over-year to 63.8 million square feet, the highest quarterly total since the fourth quarter of 2024, and expects 2026 leasing to surpass its 2022 record. JLL said leases signed over the past 12 months carried an average footprint increase of 13%, even as companies continue to downsize.
All agreed that quality continued to drive demand. Cushman & Wakefield said Class A buildings accounted for two-thirds of third-quarter leasing, well above the 10-year average of 61%. Colliers pointed to demand from AI and tech occupiers. At the same time, Lee & Associates credited stricter attendance requirements at major financial firms and AI-driven startups in San Francisco and Silicon Valley, CA.
Construction Pipeline Hits Bottom
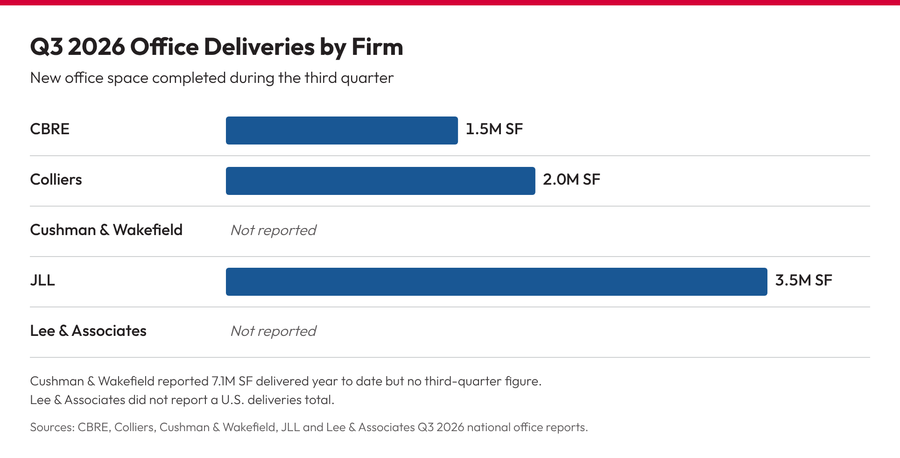
CBRE said completions fell 76% year-over-year to 1.5 million square feet, putting 2026 on track for the lowest annual total since the company started tracking in 1990. JLL said 9.6 million square feet were removed from inventory for conversions or redevelopment during the quarter; completions totaled 3.5 million square feet, and inventory has fallen by more than 45 million square feet since late 2023.
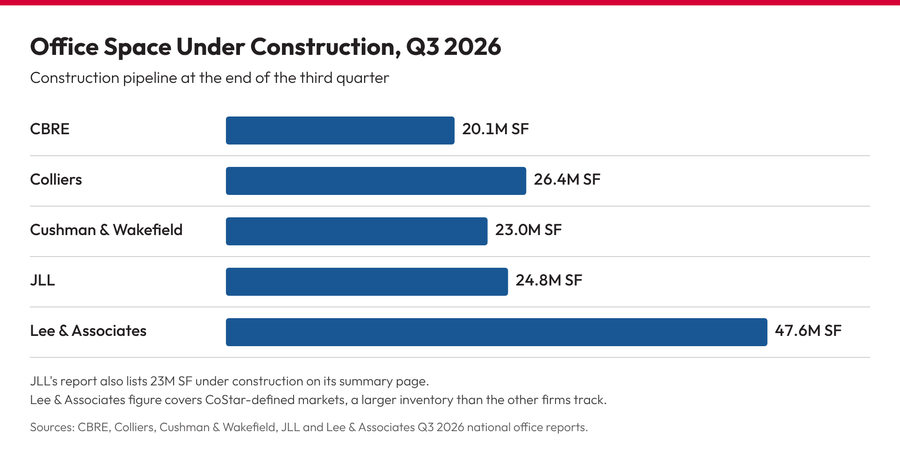
Cushman & Wakefield said 23 million square feet is under construction, a 20% increase from its Q1 low, while CBRE reported a slight rise to 20.1 million square feet, driven largely by new starts in Manhattan and Miami, FL.
Reports Split on Absorption Total
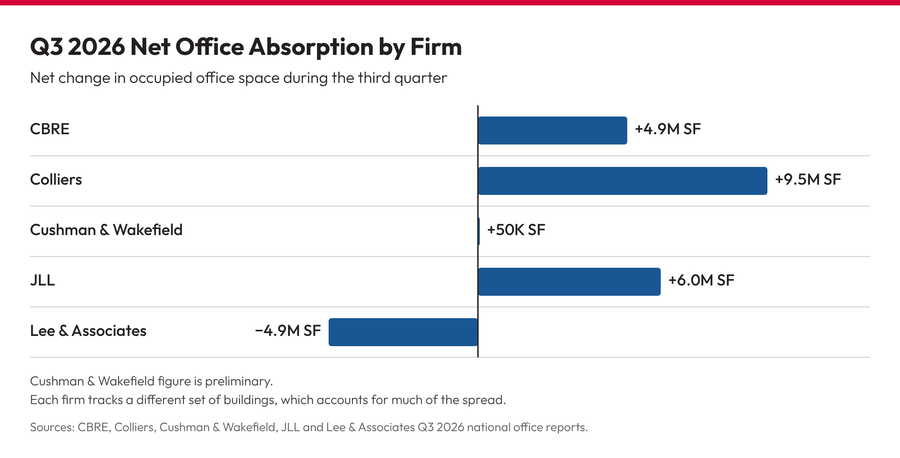
The firms agreed on most Q3 metrics. But absorption figures depended greatly on who was counting.
- Colliers put positive absorption at 9.5 million square feet of positive net absorption, the ninth consecutive positive quarter.
- JLL reported the sixth straight positive quarter, citing 5 million square feet.
- CBRE noted absorption at 4.9 million square feet, representing the 10th quarter of positive growth, while Cushman & Wakefield’s 50,000 square feet marked its fifth straight positive absorption.
- Lee & Associates said absorption was negative, ending four straight quarters of gains, with 70% of the shortfall involving Class B buildings.
The Q4 Crystal Ball
JLL expects interest rate volatility to slow some Q4 sales and delay lease decision-making. Still, tenant requirements in key markets are still above year-ago levels.
At the same time, Cushman & Wakefield said a limited construction pipeline should help protect fundamentals from economic pressures. In contrast, Colliers said it anticipates a gradual improvement versus a broader recovery.
Photo: Rawpixel.com/Shutterstock
- ◦Lease
- ◦Economy

